
Friedman proved money drives the economy.
Your Review
Friedman proved money drives the economy.
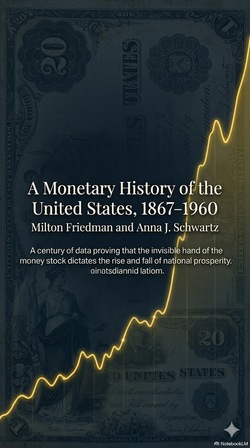
Friedman and Schwartz used 90 years of data to show the Great Depression wasn't inevitable. Between 1929 and 1933, the U.S. money supply dropped by a third, and the Fed failed to inject liquidity. This critical policy error turned a severe but short recession into a decade-long disaster because they sat on their hands while banks failed and panicked people pulled cash out of the system. The Fed should have countered the collapse instead of raising rates to defend gold, which accelerated the free fall. Their evidence that changes in money supply preceded economic shifts, not the other way around, dismantles the myth that money is just a neutral veil over real activity. The book shows how institutional choices and Fed missteps shaped America's trajectory, proving money is a powerful force that can lift economies or drag them into despair. Understanding these lessons helps us see that central bank decisions have consequences rippling across decades, making this work essential for anyone studying economic history or modern policy.
The 1931 rate hike worsened the crash. A shocking truth about policy.
Money isn't neutral.
The book shows the Fed failed during the Depression by raising rates instead of helping banks, causing a 33% money drop that turned a bad recession into a decade-long disaster where unemployment hit 25% and the economy collapsed because policymakers prioritized defending the gold standard over saving the banking system, letting panic spread as depositors rushed to withdraw cash while the Fed tightened credit further instead of injecting liquidity to stop the vicious cycle of bank failures that destroyed the money supply and deepened the crisis.
Fresh angles that made me rethink a few assumptions.
A must read for anyone who wants to understand why the Great Depression lasted so long and how central bank mistakes can create disasters.
Interesting data but feels too focused on historical Fed errors.
I was surprised to learn that the 1920s boom and bust were actually driven by the Fed's policy choices rather than just external market forces or speculation.
This book makes it clear that the Great Depression was a man-made disaster caused by the Federal Reserve's failure to act as a lender of last resort.
Friedman and Schwartz prove that money isn't just a passive tool; their evidence shows how actively managing the money supply directly shapes the economy's path.
This book changed how I see money, showing it is a powerful force that shapes booms and busts rather than just being a passive veil hiding real economic activity.
Friedman and Schwartz prove money isn't a passive veil but a powerful force shaping economic boom or bust.
This book changed how I see money. It shows the 1929 crash wasn't inevitable but caused by the Fed letting the money supply fall, proving that monetary policy choices directly create booms or busts instead of just following the real economy.
The idea that the Fed raised rates in 1931 to defend the gold standard, ignoring the collapsing domestic economy, feels like a tragic policy choice that everyone should know.
The argument that the Fed's failure to inject liquidity directly caused the Great Depression through a 33% money drop is convincing and supported by solid data.
The argument that the 1937 recession was caused by the Fed doubling reserve requirements shows how good intentions can accidentally destroy an economic recovery.
This book finally convinced me that money is not just a passive tool but a powerful force driving economic booms and busts.
The authors show how the Fed's failure to act during the Great Depression turned a manageable crisis into a decade of suffering, proving that monetary policy is never neutral and can directly cause economic disasters when leaders hesitate or make ideological mistakes instead of stabilizing the banking system to prevent a catastrophic drop in the money supply that fueled the depression.
The detailed data proves that changes in the money supply happen before economic shifts, meaning monetary policy is a powerful driver, not just a reflection, of economic activity.